A six-figure income is supposed to settle the question of whether a household can afford its rent. In New York, it doesn’t. And the first reason is hidden inside the phrase “six figures”: the census is measuring the household, not one worker.
In its 2020–24 five-year survey, the Census Bureau counts about 93,000 New York City renter households earning $100,000 or more that spend 30% or more of their income on rent, which is the official definition of being Rent-burdened Gross rent as a share of household income, using the census’s own variable. Paying 30% or more is “burdened”; 50% or more is “severely burdened”. Households with zero or negative income have no defined ratio and are excluded, as the census does.The 30% line descends from the 25% rule in the 1969 Brooke Amendment for public housing, raised to 30% in 1981. It was never designed for households earning $120,000, which is why we also look at what is left after rent. . That is a five-year average rather than a snapshot; the latest single year, 2024, is a little higher, and the FAQ gives it.
Stories about that number tend to come out the way the teller needs them to. To one side it proves that nobody can afford the city any more. To the other it proves the rent-burden statistic is broken, since it counts people making six figures. The census’s own records tell a more specific story: the salary is a poor guide to who is stretched. The six-figure households most often over the line are roommates adding up smaller incomes and people who moved in recently, and once tax and the cost of an ordinary life are counted, families with children join them, most of them from under the official line.
There are lies, damned lies and statistics, and housing statistics are among the easiest to bend, so every step here shows its work: every chart is interactive, so you can cut the data your own way, and the raw data and the code behind every number are attached at the end. The numbers are a reading of the census’s own microdata, the individual household records behind the published table, which run through 2024, the latest year the Census Bureau has released. And one thing about those records explains a surprising amount of the story: three roommates earning $60,000 each are, to the census, a $180,000 household.
About 93,000 households cross the line
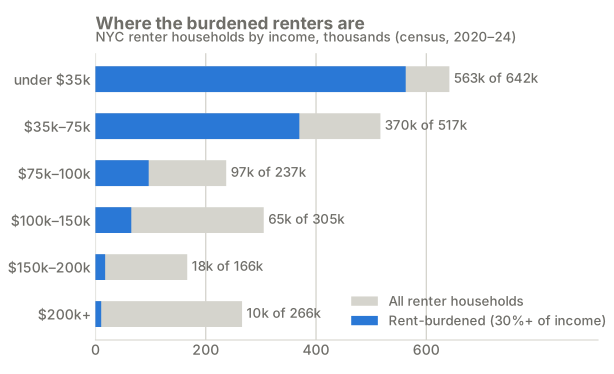
The Bureau’s published table crosses household income against rent as a share of it for every place in the country. For New York City it counts roughly 750,000 renter households at six figures and about 92,000 of them over the 30% line. Rebuilding the same count from the underlying microdata lands well inside the table’s margin of error, which is what licenses everything that follows: the rest of the story takes those same households apart in ways the table cannot.
That sounds like an enormous number. Against the city it is small. New York has about 1.1 million rent-burdened renter households, and the six-figure ones are one in twelve of them. Every other burdened renter earns less, most of them far less.
Microdata estimate Tabulated directly from survey microdata, with no model in between: every variable in the chart is observed in the same record, so the relationship shown is measured rather than modelled. It is still an estimate from a sample, not a count of everyone, and the ticks are 90% margins from the survey’s replicate weights.
How to read this, and what it cannot show
Each bar is one income band of New York City renter households; the black tick is the 90% margin of error. The household-type and borough filters apply to every band.
Has it got worse since? The census has published nothing later than 2024; the release of its 2025 survey was postponed in August 2026. What can be measured is the two sides of the ratio. Between the first eight months of 2024 and the same months of 2026, the rents New York-area tenants pay rose about 9%, by the government’s consumer price index, while average hourly pay in the city’s private-sector jobs rose about 7%.
Both indexes describe the city as a whole rather than these households, so they cannot say how many are over the line now. What they say is that the ratio behind the line has been pushed up since 2024, not down.
Rents have risen faster than pay since 2024
Survey estimate An estimate from an official sample survey read without its microdata or replicate weights: the Bureau of Labor Statistics’ monthly survey of employers (benchmarked each year to unemployment-insurance records, with the latest months preliminary), or the monthly household survey pooled by period. It carries sampling error that the publisher estimates separately; no margin is drawn here, and month-to-month wiggles are mostly noise.Rent paid by New York-area tenants and hourly pay in the city's private-sector jobs, January to August of each year, indexed so the base year chosen is 100
The interactive chart needs JavaScript; its numbers are in the table below.
How to read this, and what it cannot show
Each line is a series divided by its own value in the base year, times 100, so 109 means 9% above that year; choose 2024, the last year the census measured, or 2019. The rent line is the consumer price index for the rent of a primary residence in the New York area, the rents sitting tenants pay, stabilised and market alike, not asking rents; the pay line is average hourly earnings of private-sector employees working in the city. Each year is the average of January to August. Hover for any year’s figures. Both are BLS survey series, the consumer price index and the payroll survey’s hourly earnings, published without margins. The same numbers as paired bars are in the questions at the end.
The numbers behind this chart
About these numbers. Bureau of Labor Statistics, not seasonally adjusted: the consumer price index for rent of a primary residence in the New York area, which follows the rents sitting tenants pay, stabilised and market alike, not asking rents; and average hourly earnings of all private-sector employees working in the city, not residents' household income. Each year is the average of January to August, so the latest year compares like with like; the latest month is preliminary. Both indexes come from the Bureau's own surveys, whose sampling error it publishes separately; no margin is drawn.
| January to August of | Rent paid by New York-area tenants (CPI) | Hourly pay, private-sector jobs in the city |
|---|---|---|
| 2019 | 398.7 | $37.45 |
| 2020 | 407.6 | $38.72 |
| 2021 | 408.7 | $40.72 |
| 2022 | 415.9 | $41.22 |
| 2023 | 439.6 | $42.02 |
| 2024 | 460.1 | $42.27 |
| 2025 | 483.9 | $43.34 |
| 2026 | 503.6 | $45.18 |
A six-figure household isn’t always a six-figure earner
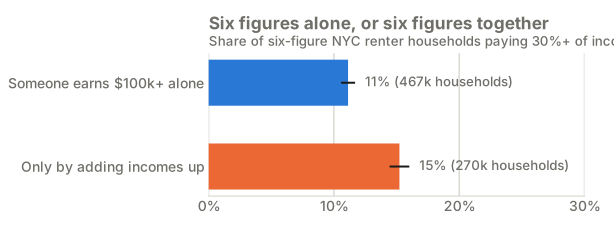
So who are they? Start with the three roommates at $60,000 each. The census interviews everyone in the apartment and writes down each person’s earnings separately; household income is those added up, along with any other income. So the two kinds of six-figure household can be told apart by looking inside. Either one person earns six figures alone, and the household would clear the bar even if that person lived by themselves, or nobody does, and the household only gets there by adding smaller incomes together, as the roommates do.
Most six-figure renter households contain someone who earns it alone. The other third and more reach six figures only by pooling, and that group is over the line more often: about 15% of them are burdened, against 11% of the households with a six-figure earner.
Microdata estimate Tabulated directly from survey microdata, with no model in between: every variable in the chart is observed in the same record, so the relationship shown is measured rather than modelled. It is still an estimate from a sample, not a count of everyone, and the ticks are 90% margins from the survey’s replicate weights.
How to read this, and what it cannot show
Filter by borough or household type; switch the measure to counts, median rent or median income. “Earns” means wages and self-employment income, not pensions, interest or benefits.
Who is doing the pooling matters even more than the pooling itself. The census sorts households into families, people living alone, and households of two or more adults who are not related to each other. For that last group it asks one further question: whether the person who answered lives with an unmarried partner. That question splits the shared households into two kinds that behave very differently. One is a couple keeping one home without being married. The other is adults who answered the same listing: roommates, in the everyday sense, or more precisely a non-partner shared household.
Couples look like families: they cross the line at about the family rate, around 11%. Roommate households do not. About 23% of them are burdened, twice the rate, and fewer than half contain anyone earning six figures alone. They are young, many of them arrived recently, and they pay about the same rent as an unmarried couple does. A meaningful part of the six-figure-renter story, then, is not a highly paid professional stretched by an expensive apartment. It is several younger workers whose combined income makes the household look richer than any of them is.
Microdata estimate Tabulated directly from survey microdata, with no model in between: every variable in the chart is observed in the same record, so the relationship shown is measured rather than modelled. It is still an estimate from a sample, not a count of everyone, and the ticks are 90% margins from the survey’s replicate weights.
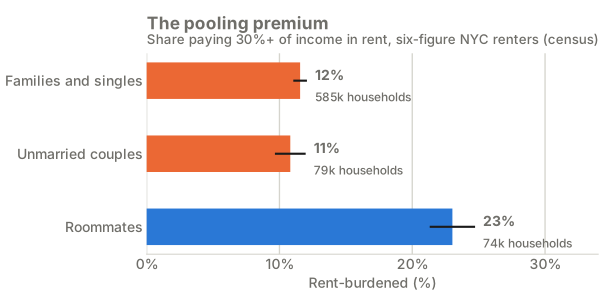
How to read this, and what it cannot show
Filter by income band and borough; switch the measure to the share of households containing a $100,000 earner. Which adult pays what share of the rent inside a shared household is not recorded.
The apartment remembers when you arrived
Pooling is the roommates’ story. The families and people living alone, four fifths of the city’s six-figure renters, have a different one, and among the dimensions examined here one of its steepest descriptive gradients is not income. It is how long ago the household Move-in year The census asks when the householder moved into the unit and reports the answer in seven bands, from “12 months or less” to “30 years or more”. Rent tends to fall with time in place because landlords raise rents on sitting tenants more slowly than the market moves, and because rent-stabilised leases cap the increase. The census cannot separate those two effects. .
Among six-figure families and singles who moved in within the last year, 22% are burdened. Among those in the same home thirty years or more, 3% are, and the steps in between fall in order, the last two within the margin of each other. Their rents fall the same way, by about half from the first step to the last. Their incomes do not: median income is highest in the first four years in the unit and changes little after that.
Microdata estimate Tabulated directly from survey microdata, with no model in between: every variable in the chart is observed in the same record, so the relationship shown is measured rather than modelled. It is still an estimate from a sample, not a count of everyone, and the ticks are 90% margins from the survey’s replicate weights.
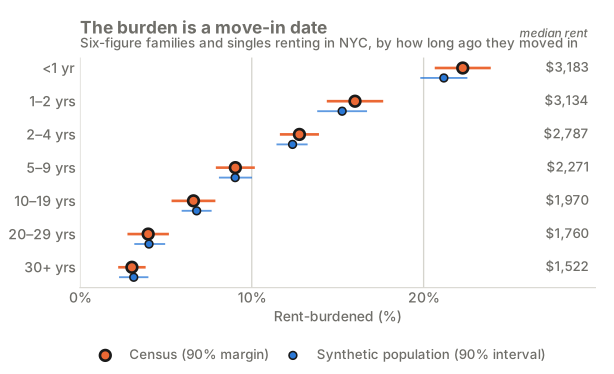
How to read this, and what it cannot show
The chart opens on families and people living alone; the type filter widens it. Switch the measure to median rent, median income, or the share living in pre-1970 buildings of five or more units, the closest census proxy for the rent-stabilised stock.
One caveat has to stay in the story, because without it the gradient is easy to misread. This is a snapshot of different households at one moment, not the same households followed through thirty years, and long-term tenants are a selected group: people with a favourable rent have more reason to stay, and people who become stretched have reason to move. So the staircase does not show that staying put causes rent burden to fall. Part of the slope is what a long tenancy does to a rent, and part is who is still there to be counted, and the census cannot separate the two. Nonetheless the pattern holds in every income band and in every borough with records enough to tell, and it is one of the strongest things the census has to say about who is over the line.
One thing has changed since the census for the stabilised apartments that the long-tenure step resembles. For renewal leases starting between October 2026 and September 2027, the Rent Guidelines Board has frozen stabilised rents, one-year and two-year leases alike, after increases of 3% and 4.5% the year before. Market leases have no such limit.
Everything above was observed. Everything below is modelled. So far every number is something the census recorded about the same household. The census can say who crosses the official line, not whether crossing it means financial strain. To ask that, the next section brings in the tax code and a cost-of-living standard, with the assumptions spelled out in the FAQ.
What the 30% rule leaves out
The official measure compares rent with income before tax. That is useful because it is simple and consistent across households, and it has been the federal convention since 1981. It is not the same thing as asking how much of the money a household actually receives goes to the rent, which is the question most people mean.
So let’s run an experiment: keep the same 30% threshold and change only the denominator. For every six-figure household in the microdata, we estimate what a New York City resident would have owed in 2024 in federal, payroll, state and city income tax, and apply the same line to what is left. Measured that way, it catches roughly a third of six-figure families and people living alone, rather than roughly one in nine under the official measure. The estimate is stylised, since the census does not say who files a return with whom, and the FAQ gives its assumptions and its range. This is not an accepted affordability standard; it is the same yardstick held against a different number, and the gap between the two is the tax.
Computed Survey records combined with published parameters, such as a tax schedule or a budget standard. The tick is the survey margin on the computed quantity; the parameters carry their own uncertainty, and the FAQ gives the range under alternative assumptions.
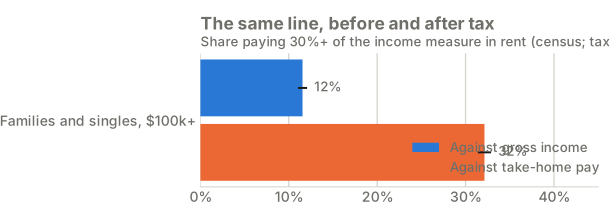
How to read this, and what it cannot show
Each pair of bars is an income band; blue is the official measure, orange applies the same 30% to estimated take-home pay. The tax is computed, not surveyed, so it carries no survey margin; the FAQ gives its assumptions and the range under different ones.
Rent burden still is not hardship. As HUD’s own research office has put it, a very high earner can spend well over 30% of income on rent and remain comfortable, and a low earner can struggle below the line. So instead of asking only what share of income goes to rent, let’s ask a plainer question: after tax and rent, can the household cover an ordinary New York budget?
New York City’s own True Cost of Living measure, released in 2026, is the starting point. It sets out what each type of household needs in total, and how that splits between housing, taxes, health care, food, transportation, child care, savings and everything else. The budget used here is SparkyData’s derivation from that measure, not a figure the City publishes: it keeps the part of each family type’s total that is neither housing, tax nor savings, and puts the household’s own rent and estimated tax in place of the measure’s. Call it a TCOL-derived residual budget. Subtract it, with the rent, from take-home pay, and ask whether anything is left.
Under the TCOL-derived budget used here, about half of six-figure families with children under 18 fall short of it. For six-figure families and singles without children, about one in six do. The budget is a standard, not a record of what any household spends, and the FAQ shows how far those shares move when the budget does. The gap between the two groups holds under every variation the FAQ tests.
Computed Survey records combined with published parameters, such as a tax schedule or a budget standard. The tick is the survey margin on the computed quantity; the parameters carry their own uncertainty, and the FAQ gives the range under alternative assumptions.
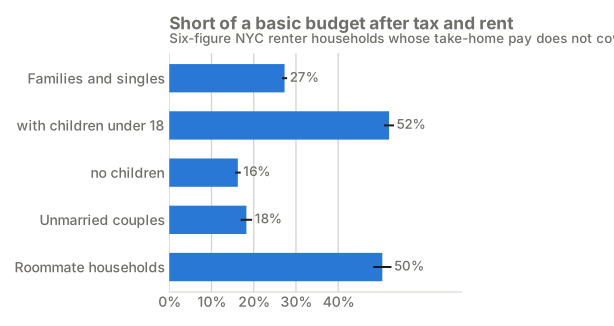
How to read this, and what it cannot show
Filter by household type, borough and whether there are children; the budget-standard menu adds the measure’s savings allowance. The measure shows the median amount left over, which is negative where the median household is short.
That is the last surprise. At this income, the difference between comfortable and stretched is often not a few percentage points of rent. It is who has to live on what remains. The households the official count flags are mostly the ones the budget flags too; but the budget also flags a great many households the official count never sees, and among families and people living alone, most of those have children.
So who is the six-figure renter?
Someone the salary describes badly. Three things the number leaves out sort six-figure households into the comfortable and the stretched: whether one person earns it or several people add it up, how long ago the household signed its lease, and who has to live on what is left after tax. On the official line, the roommates and the newest arrivals stand out, and the long-settled tenant on the same income is rarely over it, although the census cannot say how much of that is what staying does to a rent and how much is who manages to stay. On a budget that counts the tax and the cost of an ordinary life, it is families with children who stand out, most of them from under the official line.
None of that makes six-figure households the centre of New York’s affordability problem: most rent-burdened New Yorkers earn far less. But it is the case against reading a salary as a verdict. The same six figures can be three people’s modest wages, one professional’s pay or a family’s budget stretched across children, and since the census’s last year the rent those six figures have to cover has risen faster than pay. That is why the phrase “six-figure renter” is less of a contradiction than it sounds: the salary alone tells you remarkably little about the life it is financing.
Explore the data yourself
The dashboard runs on the same census records as everything above: the 26,140 microdata households earning six figures and renting in the city, each carrying its survey weight. Filter by household type, income band, borough and move-in period, and drag the slider to see how much of the count is the 30% line itself.
Rent-burdened share by move-in period, under the filters above
Loading the census records…
Every number here is a direct weighted tabulation of census microdata records, not a model prediction, so the cross-tabulations it shows are measured relationships within one survey. Their uncertainty is approximated: the headline tile carries an approximate 90% margin: a binomial margin on the record count, scaled by a design effect calibrated on the margins of the charts we walked through earlier (click the ? on the tile). Those charts carry the exact margins; treat any selection with a wide margin as indicative.
Household type
The census adds up the income of everyone in an apartment, related or not. Families and singles are family households plus people living alone. The census's shared households are two or more unrelated adults, and its HHT2 variable splits them: unmarried couples keeping one home, and roommate households, people who answered the same listing.
Unmarried couples are burdened at about the family rate; roommate households at roughly twice it. That's the second finding we saw earlier, and the filter lets you see it in every borough and income band.
Household income
Total income of everyone in the household, in constant 2024 dollars. "Six figures" means $100,000 and over. The three bands match the charts we saw earlier, so each can be checked against a bar that carries a margin of error.
Borough
Where the apartment is. The Bronx and Staten Island are combined because six-figure renters are few there. Manhattan holds 53% of burdened six-figure families and singles, Brooklyn 24% and Queens 18%.
Moved in
How long ago the householder moved into the unit, in the census's seven bands. Rents are set at signing and then drift up more slowly than the market, so a household's rent is partly a record of when it arrived. This is the filter that moves the burdened share most.
If every rent changed by…
A what-if. Each household's rent is scaled by the chosen percentage with its income held fixed, and the burdened share is recomputed. It shows how much of the count is the 30% threshold itself: many households sit just under the line.
It is not a forecast. Real rent changes are uneven, and stabilised leases cannot rise this way.
Rent-burdened
The share of the selected households whose gross rent (contract rent plus separately paid utilities) is 30% or more of household income, the census's own definition. Note that it is measured against income before tax, which is the convention every published affordability figure uses. Applied to a stylised estimate of take-home pay instead, 32% of six-figure families and singles are over the same line rather than 12%; that is an alternative yardstick, not the census definition.
This is a weighted tabulation of the census records in the selection. The charts we saw earlier show the same shares with their 90% margins of error; the dashboard shows an approximate margin beside the tile (see the ? on it); treat a wide one as indicative.
Households, weighted estimate
The sum of the survey weights of the census records in the selection, which is the Bureau's estimate of how many NYC households the records represent. Rounded to the nearest thousand. Each record stands for about 40 households, so treat a small selection as an order of magnitude.
Median gross rent
The middle household's monthly gross rent in the selection, in 2024 dollars, read off a histogram in $250 steps. For long-tenured households it lands near $1,500, which is the city's median rent-stabilised rent.
People per household
Average number of people living in the unit. Recent arrivals are mostly one or two people; households ten years in are typically families of three.
Median householder age
The age of the person the census records as the householder, in five-year steps. It rises from the early thirties among the newest arrivals to the late sixties among households thirty years in.
Pre-1970 buildings of 5+ units
The census does not record whether a lease is rent-stabilised. Stabilisation covers buildings of six or more units built before 1974, and the closest cut the census allows is five or more units built before 1970. This is a proxy for the stabilised stock, not a count of stabilised leases.
The staircase
Each bar is the rent-burdened share for one move-in period, under the type, income and borough filters. Choosing a move-in period highlights its bar rather than hiding the others, so the slope is always visible. The rent slider shifts every bar.
The ± figure
An approximate 90% margin of error on the headline share. The dashboard cannot carry the 80 replicate weights behind the charts we saw earlier, so it estimates the margin as 1.645 × √(deff × p(1 − p) ÷ n): n is the number of census records in the selection and deff is the design effect, the ratio of the survey's true sampling variance to that of a simple random sample of the same size.
The design effect is calibrated from those charts: for every chart cell, (replicate-weight margin ÷ binomial margin)², and the median is used. The note under the chart gives the effective sample size, n ÷ deff. For any cut the charts precompute, the chart's margin is the exact one.
Too few households
Fewer than 30 census records match, so the numbers would be noise. Widen a filter.
Questions this raises
Why are so many six-figure New Yorkers renters in the first place?
Partly because a six-figure salary does not stretch far in the city’s housing market. The median American home is worth about $332,700, a little over three times a $100,000 salary, the kind of ratio that lenders’ affordability rules are built around. In New York City the median home is worth $777,600, nearly eight times that salary, and it is not a house: in Manhattan that money buys a one-bedroom co-op, whose median sale price was $690,000 at the end of 2025, and falls well short of a one-bedroom condo at $1,075,000. Whether a particular household can buy depends on its savings, its debts, the mortgage rate and the home itself, so the ratio is context, not a lending test. About two thirds of the city’s 3.4 million households rent.
What exactly does “rent-burdened” mean, and where does the 30% rule come from?
The census’s own definition: Gross rent Contract rent plus the utilities and fuel the household pays separately, as the census defines it. It is the numerator of the burden ratio and is what we mean by “rent” throughout. Medians are weighted medians of the households in the group. , which is contract rent plus separately paid utilities, at 30% or more of household income before tax. Paying 50% or more is “severely” burdened. The standard descends from the 1969 Brooke Amendment, which capped public-housing rents at a quarter of a tenant’s income, and was raised to 30% in 1981; HUD’s definition of a cost-burdened household has been written against gross household income ever since. Personal-finance advice is split: some of it repeats the 30%-of-gross rule, while the popular 50/30/20 budgeting rule is written against take-home pay.
How close is this count to the Bureau’s published one?
The published table reports 751,373 ± 7,458 six-figure renter households and 92,322 ± 3,066 of them paying 30% or more. Rebuilding the same universe from the microdata gives 737,579 households (the table’s universe includes about 15,000 households whose ratio could not be computed) and 93,177 ± 3,429 burdened, a difference of 855, about a quarter of either Margins of error from replicate weights Each PUMS record carries 80 replicate weights alongside its main weight. A statistic is recomputed 80 times, once with each replicate, and the spread of those 80 answers around the main answer gives its standard error: variance = 4/80 × Σ(θr − θ)². The Census Bureau reports 90% margins, 1.645 standard errors, and every census margin we show follows that convention.This is the Bureau’s own method (successive difference replication), so a margin here matches what the Bureau would publish for the same cut. . The city has 2,133,000 renter households with positive income, 1,122,000 of them burdened.
What counts as “earning” six figures?
Wages, salary and self-employment income, which the census records for each person as earnings. Pensions, interest, dividends, Social Security and other benefits count toward household income but not toward whether someone is a six-figure earner. On that definition 63% of six-figure renter households contain a person earning $100,000 or more and 37% reach the line only by pooling. Counting a person’s total income instead of their earnings would put the split nearer 68% and 32%; the burden rates of the two groups are the same either way.
What exactly counts as a “roommate household”?
The census’s nonfamily households whose householder does not live alone, minus those where the householder reports an unmarried partner. It is the survey’s classification, not the respondents’ description of themselves: two unrelated adults who consider themselves partners but are not recorded as such count as roommates, and a household of a householder, their partner and a third adult counts as a couple. The charts label the group “non-partner shared” for that reason. Six-figure unmarried couples number about 79,000 households and roommate households about 74,000. The median adult in a roommate household is in their late twenties, and half of those households moved in within the last two years. The census records one rent per apartment, so a pooled household’s burden is measured against its combined income whether or not the members pool in practice.
Who else lives on each step of the move-in staircase?
Different people, paying different rents. Families and people living alone are four fifths of the city’s six-figure renters, and about 68,000 of them are burdened. Their median rent falls from about $3,200 a month on the newest step to about $1,500 on the oldest. The newest arrivals average 2.1 people, nearly half live alone, and the median renter among them is 34. Ten years in, the household averages 3.2 people, 38% have children, and the median renter is 46. Thirty years in, the median renter is 58 and 78% of the households live in pre-1970 buildings of five or more units, against 41% of the newest arrivals. Households less than two years in the unit are a quarter of the group and 45% of its burdened. The census does not record which leases are stabilised, so the building proxy is the closest it gets.
Is a $1,500 rent on a six-figure income believable?
A six-figure household paying $1,500 a month in Manhattan invites the obvious objection: why has the landlord not found a way to move them out?
The rent itself is unremarkable for its kind. The city’s 2023 Housing and Vacancy Survey puts the median gross rent, the same rent-plus-utilities measure the census uses, at $1,570 for rent-stabilised units, against $2,115 for market rentals and $1,695 citywide; the contract rents, before utilities, are $1,500, $2,000 and $1,641. The Furman Center finds average tenure of eight years in stabilised units against three in unregulated ones, which is the move-in staircase seen from the other side.
The census cannot say which apartments are stabilised, so the honest statement is that the pattern is consistent with stabilisation rather than evidence of it: low rents, long tenancies and pre-1974 multi-unit buildings travel together, and that is the stock stabilisation covers. Where stabilisation does apply, a tenant has a right to a renewal lease and the increase is set annually by the Rent Guidelines Board. A unit could once leave stabilisation if its tenants earned over $200,000 for two consecutive years and the rent was already high; the Housing Stability and Tenant Protection Act of 2019 repealed that. High income is not a ground to refuse a renewal.
Nor are these apartments mainly a perk of the well-off. The Housing and Vacancy Survey, as reported by the Rent Guidelines Board, finds that 30% of rent-stabilised units are occupied by households earning $100,000 or more, against 47% of market-rate rentals, and the Furman Center puts the median stabilised household’s income near $60,000. The six-figure households on the bottom step are a minority of stabilised tenants who moved in decades ago and stayed.
How were taxes estimated, and how accurate is it?
For each household: 2024 federal income tax, the employee half of social security and Medicare, New York State income tax including the state’s recapture of lower-bracket benefits above $107,650 of income, and the city’s resident income tax of up to 3.876%, with the child tax credit for each related child under 18 in the household, a year above the credit’s own age limit, from the published 2024 schedules and worksheets; the credit for other dependents is not claimed, since the census does not say who is a dependent. Filing status is inferred from who lives in the household and is an approximation; in a shared household each adult is taxed separately on their own income.
It is a stylised estimate, not a reconstruction of anyone’s return. Giving every household the standard deduction over-taxes anyone who would itemise, and leaving out the earned-income, dependent-care and school tax credits over-taxes eligible households, while treating every family household as one return can go either way; the direction of the net error is unknown. As an envelope, recomputing with every household’s tax bill ten percent lower or ten percent higher moves the share of six-figure families and singles over the 30% line on take-home pay, 32% as estimated, between 29% and 36%. In round figures, taking the median of each quantity separately, so they need not add up to one household: the burdened six-figure household’s median income is $123,400, its median combined tax about $35,600, an Effective tax rate Total tax as a share of total income, not the top marginal rate. A New York City household earning $123,000 pays about 28% of it in federal, payroll, state and city tax combined, while the highest bracket its last dollar touches is 22% federal alone. of 28% on average, its median take-home pay about $89,400 and its median rent $3,923, and the median such family pays 35% of its gross income and 49% of its Take-home pay Household income after federal income tax, the employee share of social security and Medicare, New York State income tax and New York City resident income tax, computed from the 2024 schedules for the household’s filing status. In a shared household each adult is taxed separately, which is what the law requires.The child tax credit is applied for the household’s related children under 18, and New York’s recapture above $107,650 is included. A stylised estimate, not a reconstruction of a return: census income is not taxable income and the survey records no deductions or filing details. Giving everyone the standard deduction and omitting the other credits makes it too high; treating each family household as one return can go either way. The net direction is unknown. in rent.
Is a census household the same as a tax return?
No, and this is the biggest approximation in the modelled half. A census “family household” can contain a married couple, an adult child, a grandparent and a sibling, who may file three or four separate returns; the estimate files one. So everything after-tax was rerun on the households where one return is clearly right: a person living alone, a married couple with no other adult, and a couple or single parent whose other members are all children under 18. That is 65% of six-figure families and singles. On that clean subset the share over the 30% line on take-home pay is 37%, higher than the 32% headline, because the households left out, the ones with extra adults, have more income per return than the pooled figure implies and are over the line at 22%. The budget test moves the other way: 18% of the clean subset cannot cover rent plus the TCOL-derived budget, against 27% of all families and 45% of the complex households, which more often have children and have lower incomes set against larger family budgets. Among families with children the clean subset is over the after-tax line at 28% and short of the budget at 43%, against 26% and 52% for all of them. The findings hold on the clean subset; the exact percentages for complex households depend on how their returns are split, which the census cannot say.
Isn’t the after-tax measure just a different affordability standard?
It is the same 30% threshold applied to a different denominator, and it is not endorsed by anyone as an official standard. The two measures answer different questions. The official statistic measures housing cost consistently across every household in the country. The after-tax version gets closer to the money a household has available, and the gap between them, in a city that levies its own income tax on top of the state’s, is the tax.
How much income does it take to rent at the going rate after tax?
The City Comptroller priced the citywide asking rent at $3,500 a month in January 2024 and reported that a household needs about $140,000 to pay it without being burdened, which is 30% of gross income. Ask instead what salary leaves $3,500 at 30% of take-home pay and the answer is about $217,000 for a single filer, or $201,000 for a married couple splitting the same wages. The $140,000 is not wrong; the two numbers apply the same threshold to different denominators, and the gap between them is the tax.
What is the TCOL-derived budget, and does failing it mean hardship?
The City’s 2026 True Cost of Living measure gives the median annual cost of living by family type and its components (housing, health care, food, transportation, child care, savings, taxes, other), in 2022 dollars. The budget used here keeps the part of each family type’s total that is neither housing, tax nor savings (about 48% for adults without children, 56% with children, 46% for households headed by someone 65 or over) and carries it to 2024 dollars with the New York-metro consumer price index. A single adult under 65 gets about $36,000 a year; a family with children about $90,000, most of the difference being child care and health care. Roommate households are budgeted one adult at a time, which likely overstates their costs, since unrelated adults sharing an apartment also share some expenses that the single-adult budget prices separately. Budgeting them on the City’s two-adult figure instead, with the two-adult increment for each further adult, lowers the share of roommate households short of the budget from 50% to 43%; on a square-root scale, where two adults need 1.4 times one adult’s budget, it falls to 14%. The per-adult budget stays the main one because the City’s two-adult figure is for a couple keeping one home, and the square-root scale assumes more sharing than people who split a listing are likely to do; the range says how much the roommate result rides on that choice. A single parent aged 65 or over takes the under-65 figure, which the measure suppresses. The City does not publish this residual budget; it is derived from the City’s tables, and it inherits the tax estimate’s assumptions about who files with whom.
Failing it does not mean hardship, and the shares move with the standard: shifting the budget ten percent either way moves the share of six-figure families with children who fall short between 43% and 59%, and the share of those without children between 11% and 22%. The budget is a median for a family type, actual spending is unobserved, and a family paying less than the median for child care, or none, has more room than the arithmetic shows, while a family with a disabled member or student debt has less. Among all six-figure families and singles, 27% are short of the basic budget (21% to 33% with the budget moved ten percent either way, 24% to 31% with the tax moved); among the rent-burdened ones, 63%, with a median shortfall of about $9,600 a year. Adding the measure’s savings allowance raises the share of families with children who are short from 52% to 63%.
How do six-figure renters compare with everyone else?
About 63% of the city’s renter households have less left after their own tax and rent than the median burdened six-figure household does. The stress is real at this income; it is also the stress most of the city lives with, at incomes where the ratio never needed a second look.
What about the owner next door?
The same 30% line applies to owners, counting mortgage payment, property taxes, insurance, utilities and condo fees as Owner costs, same 30% line For owners the census computes selected monthly owner costs as a share of income: the mortgage payment (principal and interest), property taxes, insurance, utilities and any condo or co-op fees. The same 30% threshold applies. Principal repayment is savings rather than spending, and the yardstick does not distinguish, so owner burden overstates hardship in the way renter burden does not. . About 25% of six-figure New York owners with a mortgage are over it, roughly 102,000 households against 93,000 burdened renters.
Microdata estimate Tabulated directly from survey microdata, with no model in between: every variable in the chart is observed in the same record, so the relationship shown is measured rather than modelled. It is still an estimate from a sample, not a count of everyone, and the ticks are 90% margins from the survey’s replicate weights.
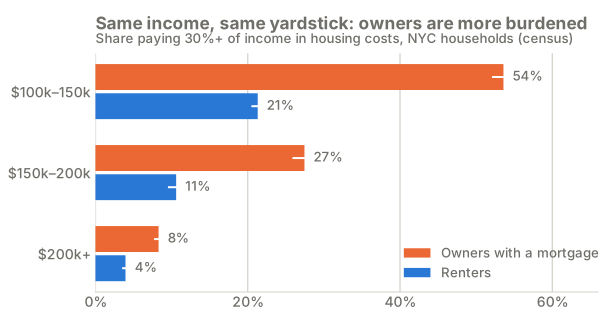
How to read this, and what it cannot show
Owners with a mortgage against renters, by income band, at the 30% or the 50% threshold, with the same type and borough filters as the renter charts. These are different households observed at the same moment, not the same household under two choices; owner cost includes mortgage principal, which builds equity, and property tax, which a renter pays indirectly through the rent.
Isn’t a five-year census file distorted by the pandemic?
The estimates come from the 2020–2024 five-year file, which pools five survey years to get a sample large enough to cut this finely, and that average contains the pandemic rental market. Recomputing the headline cuts on the 2024 one-year file, with its smaller sample and wider margins, the picture holds, at a slightly higher overall rate. The burdened share of six-figure renter households is 14.1% ± 0.9 in 2024 against 12.6% across the five years. Roommate households remain the outlier at 23.3% ± 3.1, against 12.8% ± 0.9 for families and singles and 14.0% ± 2.7 for unmarried couples. The move-in gradient still runs from about 24% among the newest arrivals to under 4% among households thirty years in.
What has changed since 2024?
The census has not yet published a year after 2024: its 2025 results were due in September 2026 and have been postponed while the Census Bureau adapts them to a Commerce Department order on disclosure protection, so every count above is still the latest there is. Two published indexes carry the two sides of the ratio forward. The consumer price index for the rent of a primary residence in the New York area, which follows the rents sitting tenants pay, stabilised and market alike, averaged 9.4% more from January to August 2026 than in the same months of 2024, and 26.3% more than in 2019. Average hourly earnings of private-sector employees working in the city rose 6.9% from 2024 and 20.6% from 2019; weekly earnings 6.7% from 2024. Prices as a whole in the New York area rose 7.9% from 2024. So rent has risen faster than pay since the census, as it did between 2019 and 2024.
Neither index is these households. The rent index includes the long-tenure stabilised leases whose increases are set by the Rent Guidelines Board, and it moves more slowly than the asking rents a new tenant faces; the pay series is for jobs located in the city, including those held by commuters, and says nothing about a household’s number of earners. What they support is a direction: the ratio behind the 30% line was pushed up between 2024 and 2026, not down.
For stabilised tenants the increases themselves are published. Renewal leases starting between October 2025 and September 2026 could rise by 3% for one year or 4.5% for two; for leases starting between October 2026 and September 2027 the Board voted in June 2026 to freeze both at 0%, the first freeze of a two-year lease. Market leases are not covered.
Here are the two indexes as paired bars, set to 100 in 2024:
Survey estimate An estimate from an official sample survey read without its microdata or replicate weights: the Bureau of Labor Statistics’ monthly survey of employers (benchmarked each year to unemployment-insurance records, with the latest months preliminary), or the monthly household survey pooled by period. It carries sampling error that the publisher estimates separately; no margin is drawn here, and month-to-month wiggles are mostly noise.
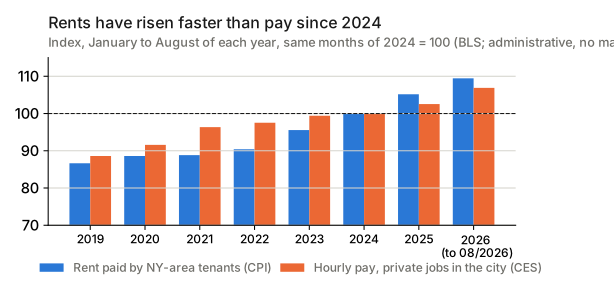
How to read this, and what it cannot show
Blue is the consumer price index for the rent of a primary residence in the New York area, the rents sitting tenants pay, stabilised and market alike, not asking rents; orange is average hourly earnings of private-sector employees working in the city. Each is averaged over January to August of each year and set to 100 in 2024. Both are BLS survey series, the consumer price index and the payroll survey’s hourly earnings, published without margins.
Is this analysis built on SparkyData’s synthetic population?
No. SparkyData maintains a 500,000-person The synthetic population SparkyData’s New York metro release samples whole households from the census microdata, re-weights them to published totals by region, tenure, household size, income and age, and layers on attributes the census does not ask about. No record is a real person, but each household’s income, rent, size, borough, move-in year and members’ earnings came together from one real record, so those relationships are inherited, not modelled.We use only inherited variables. The modelled wealth layer was deliberately left out; the notebook explains why. resampled from this microdata and re-weighted to published totals, but no number here comes from it: every variable the question needs is jointly observed in the census, which answers directly and with a tighter margin. The reproduction table records, as a calibration check rather than a test, that the population lands inside the What “within band” means Each check has a band that combines two uncertainties: the census margin of error on the published value, and the sampling error a synthetic population of this size carries on the same statistic. A miss is a difference larger than the band. At 500,000 people the second term is small, so the bands are close to the census margins themselves. on all fourteen renter statistics it is checked against, eleven of them The held-out reproduction check The rent-burden statistics were computed from the census microdata after the synthetic population was built and were never used to calibrate it. Reproducing them shows that re-weighting to the published margins did not distort the relationship between rent and income.It is not an out-of-sample test: the synthetic households are sampled from the same microdata, so agreement is expected. It is a check that nothing broke, and it should not be read as more than that. rent-burden shares.
What can this data not tell us?
Anything below the Microdata areas The smallest geography in the census microdata is the Public Use Microdata Area, a cluster of one or two community districts with roughly 100,000 people. Manhattan has ten. Any claim below that scale is not supported by the data, which is why we never go below it. scale. Which leases are stabilised. Whether a household is burdened by choice. How rent is divided inside a shared household. Who files a tax return with whom. Actual spending, or anything about wealth: no public survey observes a New York household’s rent and its balance sheet together. Whether staying in an apartment causes burden to fall, which would need the same households followed through time. And the microdata is itself a disclosure-protected sample of the survey, with top-coded rents and incomes and some perturbation, so every joint observed in it is an estimate of the city’s joint rather than the joint itself.
Under the hood: data, definitions, estimators and the full results
This is the methods note for everything above. It is deliberately more technical than the rest, and it does not repeat the tax and budget questions answered in their own entries above.
Census microdata. The 2020–24 five-year public-use microdata sample for a 156-area study region covering the five boroughs, Long Island, the lower Hudson Valley, twelve northern New Jersey counties and southwestern Connecticut: 412,280 housing-unit records and 926,174 person records with their 80 replicate weights. Dollars are carried to Income bands and 2024 dollars All incomes and rents are in constant 2024 dollars, using the Census Bureau’s own adjustment factors for the five survey years. The bands are the ones the release’s verification targets use: under $35,000; $35,000–75,000; $75,000–100,000; $100,000–150,000; $150,000–200,000; $200,000 and over. By “six figures” we mean household income of $100,000 and over. with the Bureau’s own income and housing adjustment factors. The analysis universe is occupied rental units in the five boroughs with positive household income and a defined rent-to-income ratio, 2.13 million weighted households. The 2024 one-year file, with its own replicate weights, is used only for the sensitivity check below.
Definitions. Rent is gross rent, and burden is the Bureau’s own rent-to-income percentage at 30%, top-coded at 101. “Earner” throughout means the highest own earnings in the household — wages plus self-employment income; total personal income, which adds pensions, interest and transfers, would put the earner share at 68.1% rather than 63.4%. Move-in period is when the householder moved into the unit, in seven bands: it is a move-in period, not a lease date, and a tenant may have renewed many times since. Families and singles are family households plus householders living alone; shared households are nonfamily households whose householder does not live alone, split by the survey’s partner question into cohabiting couples and households whose householder lives only with nonrelatives. The stabilised-stock proxy is buildings of five or more units built before 1970. The survey does not record rent regulation.
Estimators. For a statistic computed with the full weight, the same statistic is recomputed with each of the 80 replicate weights and the variance is the Bureau’s successive-difference estimator, four-eightieths of the summed squared deviations of the 80 replicate estimates from the full-weight one. Margins are the Bureau’s 90% level, 1.645 standard errors. Counts are weighted sums, shares weighted means, medians weighted medians without a margin. Every combination the chart controls can reach is precomputed with the same estimator and a margin on each bar; a cell resting on fewer than 30 records is labelled too thin rather than drawn.
Does it reproduce? The published table and this tabulation describe the same universe by different routes. The table reports 751,373 households at $100,000 or more with 14,884 ratios not computed, leaving 736,489 in the universe; the microdata gives 737,579, a difference of 1,090 or 0.15%. The table reports 92,322 ± 3,066 burdened; the microdata gives 93,177 ± 3,429, a difference of 855, which is 28% of the published margin and 25% of ours. Both are the Bureau’s own data, so this checks the construction of the universe rather than either estimate’s accuracy — which is what had to be established before cutting the universe in ways the published table cannot. It has no household-composition dimension, no move-in dimension, and no way to apply any yardstick other than the one it prints.
Six figures alone, or by pooling. Of 737,579 six-figure renter households, 467,492 ± 6,140 (63.4%) contain a person earning $100,000 or more and 270,087 ± 5,162 reach the line only by pooling. The pooled households are burdened at 15.2% ± 0.8% against 11.1% ± 0.6%, with a median household income of $132,946 against $203,888, a median gross rent of $2,162 against $2,926, and a median of three people against two. Roommate households are 14.8% of the pooled group and 7.3% of the earner group.
Composition. Families and singles: 584,601 households, burdened at 11.6% ± 0.5%, 65% containing a six-figure earner. Unmarried couples: 78,649 households, 10.8% ± 1.2%, 68%. Roommate households: 74,329 households, 23.0% ± 1.7%, 46%. Cohabiting couples are 51.4% of six-figure shared households and their burden rate sits inside the margin of families and singles, so reporting the two shared groups together would average a factor of two into one number. The composition variable accounts for the gap: about seven in ten unmarried-couple households contain an individual six-figure earner against fewer than five in ten roommate households, and the two shared groups are of similar age — median householders of 31 and 29 against 42 for families and singles — so age is not what separates them. The 93,177 burdened households are 67,557 families and singles, 8,507 unmarried couples and 17,113 roommate households.
The move-in gradient. For families and singles, burden falls from 22.3% ± 1.6% at twelve months or less to 3.0% ± 0.8% at thirty years or more, and median gross rent from $3,183 to $1,522. Median household income does not fall in step — it is highest in the first four years in the unit, between $168,138 and $178,986, and $151,938 among households thirty years in — so the gradient is not an income gradient in disguise. The newest arrivals average 2.1 people, 47% live alone, 55% occupy studios or one-bedrooms and the median householder is 33; at ten to nineteen years the household averages 3.2 people, 38% have children and the householder is 50; at thirty years or more the household averages 2.5, 14% have children, the householder is 68, and 78% ± 2% live in pre-1970 buildings of five or more units against 41% ± 2% of the newest arrivals. Two limits. It is a cross-section and the causal reading is not available from it: rents set at signing rise more slowly than the market, households that became burdened had reason to move, households whose income rose in place had reason to stay, and there is a selection effect on the composition of each step that the five-year file cannot separate. And a strong bivariate gradient is not a ranking of predictors — establishing that move-in period outranks income, borough, unit size, composition or building would need a model with those variables and an out-of-sample criterion, which this analysis does not run. The claim is only that, with income in the three bands used here, move-in period carries a descriptive gradient at least as steep as income’s; banded more finely, income’s is steeper.
Do the long-tenure rents hold up? A median gross rent of $1,522 for six-figure households thirty years in the unit is consistent with independent evidence, compared like with like: the 2023 Housing and Vacancy Survey’s median gross rent, contract rent plus separately paid utilities, was $1,695 citywide, $1,570 for rent-stabilised units and $2,115 for market rentals in 2023 dollars (the contract-rent medians are $1,641, $1,500 and $2,000). The Furman Center reports an average tenure of eight years in stabilised units against three in unregulated ones, a median stabilised-household income near $60,000, and that about 65% of the stabilised stock entered stabilisation because it was built before 1974. In the microdata the all-income median rent of households thirty years in the unit is $1,202, and 77% of them live in the proxy stock. Since the survey does not record regulation, the pattern is consistent with stabilisation rather than an identification of stabilised tenancies. Where stabilisation applies the tenant holds a statutory right to a renewal lease, and the high-income deregulation provision was repealed in 2019, so income is not a ground for non-renewal, though other legal grounds for eviction remain.
What is left, by household size. People living alone are burdened at 17.5%, roughly twice the rate of larger households, because one income pays a whole rent. The amount left after tax and rent barely moves across household sizes, from about $40,000 to $52,000, so the amount per person falls by two thirds, from $40,100 to $13,100. That is why this group is not characterised as in or out of hardship: a single person keeping $40,000 and a family of four keeping $13,100 each are over the same line, and separating them needs a household-size-adjusted budget standard this analysis does not apply. What can be said is that 62.7% ± 0.3% of all city renter households have less left after their own tax and rent than the median burdened six-figure household.
Owners on the same line. Applying the same 30% to selected monthly owner costs for owners with a mortgage, 24.8% ± 0.6% of the 410,500 six-figure owner households are cost-burdened, about 102,000 against 93,200 burdened six-figure renters of all types. By band: 53.6% ± 1.5% at $100–150k against 21.3% for renters, 27.4% ± 1.6% at $150–200k against 10.6%, and 8.3% ± 0.6% above $200k against 3.9%. Owner costs include principal repayment and property tax, so this compares positions relative to the same line, not hardship. These are different households seen in cross-section, not the same households under alternative tenure, and we can’t say what would have happened had a given renter bought. The tax estimate is not extended to owners, because doing that honestly would need the mortgage-interest and property-tax deductions, which the survey does not support.
Sensitivity: the 2024 one-year file. The five-year file pools 2020–24 and so carries the pandemic rental market in its average. Recomputed from the 2024 one-year file on the same universe and definitions, with its smaller sample and wider margins, the burdened share of six-figure renter households is higher in 2024 alone than across the five years, and every qualitative finding holds: roommate households remain the outlier, unmarried couples remain within the margin of families, and the move-in gradient still runs from about 24% to under 4%.
Since 2024. The census’s 2025 one-year release is postponed, so the counts stop at 2024. The two indexes in Figure 2 are the Bureau of Labor Statistics’ consumer price index for the rent of a primary residence in the New York-Newark-Jersey City area (CUURS12ASEHA) and the Current Employment Statistics average hourly earnings of all private-sector employees in New York City (SMU36935610500000003), with all items and average weekly earnings beside them, retrieved through the Bureau’s public interface. Both are monthly and not seasonally adjusted, so each year is the mean of January to August, the months 2026 has, indexed to the same months of 2024; no October 2025 price index was published. They don’t measure the households we counted, and no count of burdened households is projected from them. The Rent Guidelines Board’s orders are transcribed from its published guidelines.
Limitations, stated plainly. Vintage: the five-year file averages 2020–24, and the one-year check above is the test. Regulation: the survey does not record stabilisation and the building proxy is coarse in both directions. Top-coding: gross rent is top-coded and high incomes are component-top-coded. Taxes: a stylised estimate with omissions in both directions; survey money income is not adjusted gross income and filing status is inferred. Causality: the move-in gradient is a cross-section subject to selection, and no ranking of predictors is claimed. Hardship: assessed only as the arithmetic of a standard budget, where actual spending is unobserved and the budget is a family-type median. Geography: nothing below the microdata area is supported. Composition: two unrelated adults who consider themselves partners but are not recorded as such are counted as a roommate household.
Rerunning it. The analysis script computes every number and figure above and the bar charts, from seed 20240101; the template charts and the dashboard come from two further steps of the same code, and the build manifest lists every module of it, and of the shared library of readers and estimators it imports, with its checksum. Its docstring is the long-form method, and tax_nyc.py carries the tax calculator and its self-test against hand-worked returns. Parameters live in taxes_2024.yaml and cost_of_living_nyc.yaml. The reproduction table is the synthetic population’s check against fourteen published renter statistics, described in the questions; the reconciliation with the published table is in the Reproduce box. The companion dataset is the census records themselves: the 26,140 six-figure city renter households with their survey weights, the derived variables, the estimated tax and the assigned budget, so a weighted sum of its burdened column reproduces the headline count. Reproducing the margins needs the replicate weights and the full extract, which the fetch step downloads rather than ships.
Continue exploring New York
Not just the cold: thirty winters of heat in New York
Last winter's record of about 305,000 no-heat complaints was not just the cold: at the pre-pandemic rate its weather would have brought about 206,000; it brought 48% more.
Who gets the rent freeze
A rent freeze can't pick its tenants, and how its value splits depends on the yardstick: in dollars, better-off households get a little more than their share, because they pay higher rents; against income, the poorest gain the most.
- Explore this dataset: the data and the code behind every number above.
- All articles · Search · RSS
SparkyData Weekly
Once a week, one New York theme: what the public data says about it, and the week's new articles.
Free, weekly, and one click to leave. Your address is held by Buttondown, which sends it; see the privacy policy.
Sources
- U.S. Census Bureau — Household Income by Gross Rent as a Percentage of Household Income, New York city (ACS 2020–2024 5-year, table B25074) — 751,373 ± 7,458 renter households at $100,000 or more; 92,322 ± 3,066 of them paying 30% or more; the published count we start from
- U.S. Census Bureau — ACS 2020–2024 5-Year PUMS (NY, NJ, CT), housing and person files with replicate weights — every count, share and margin labelled census; the 2024 1-year file is used for the sensitivity check
- U.S. Census Bureau — Tables B25077, B25064 and B19013, United States and New York city (ACS 2020–2024 5-year) — median home value $332,700 nationally against $777,600 in the city; median gross rent $1,413 against $1,821; median household income $80,734 against $80,483
- NYC HPD — 2023 New York City Housing and Vacancy Survey, Selected Initial Findings — 2,324,000 renter-occupied and 1,109,000 owner-occupied households in 2023; citywide median contract rent $1,641; rent-stabilised $1,500; market $2,000 (2023 dollars). The report's 'monthly rent' is contract rent; gross rents are in the RGB study below
- Douglas Elliman / Miller Samuel — The Elliman Report, Manhattan Sales, Q4 2025 — median sales price of a one-bedroom co-op $690,000 and of a one-bedroom condo $1,075,000, Manhattan, fourth quarter of 2025
- New York City Rent Guidelines Board — 2024 Income and Affordability Study — from the 2023 HVS: 30% of rent-stabilised units had household income of $100,000 or more, against 47% of market rentals (p. 13); median gross rents from the 2023 HVS: $1,695 citywide, $1,570 rent-stabilised, $2,115 market
- Internal Revenue Service — Revenue Procedure 2023-34 (2024 rate schedules and standard deduction) — federal brackets and the $29,200 / $21,900 / $14,600 standard deductions used by the tax calculation
- Internal Revenue Service — Publication 15 (Circular E) and Publication 17, 2024 — social security 6.2% to a $168,600 wage base and Medicare 1.45%; the $2,000 child tax credit and $500 credit for other dependents
- Internal Revenue Service — Instructions for Schedule 8812, 2024 — the credit phase-out above $200,000 of income, or $400,000 filing jointly
- New York State Department of Taxation and Finance — Instructions for Form IT-201, tax year 2024 — New York State rate schedule and standard deduction, the tax computation worksheets for New York AGI above $107,650 (pages 34–39), and the New York City resident rate schedule of 3.078% to 3.876%
- U.S. Department of Housing and Urban Development, PD&R Edge — Rental Burdens: Rethinking Affordability Measures (2014) — the 30% standard: 25% of income under the 1969 Brooke Amendment, raised to 30% in 1981, defined against gross household income; and HUD's own critique that the ratio says nothing about what is left over
- NYC Mayor's Office of Equity and Racial Justice — The True Cost of Living in New York City, 2026 TCOL Measure — median annual cost of living by family type (single adult $70,334; two adults, two children $166,279) and its components: housing, health care, food, transportation, child care, savings, taxes, other (Tables 2 and 3, 2022 dollars); the budget used here is derived from these, not published by the City in this form
- Office of the NYC Comptroller — Spotlight: New York City's Rental Housing Market (Jan 2024) — half of renters burdened (ACS 2022); citywide asking rent $3,500; $140,000 of income to afford it under the conventional gross-income rule
- NYU Furman Center — Understanding Different Segments of New York City's Rent-Stabilized Housing Stock — median stabilised-household income about $60,000; average tenure eight years in stabilised units against three in unregulated; about 65% of the stabilised stock is pre-1974 buildings
- NYC Rent Guidelines Board — Rent Laws of 2019 (Housing Stability and Tenant Protection Act) — repeal of high-income deregulation; a stabilised tenant's right to a renewal lease is not conditioned on income
- U.S. Bureau of Labor Statistics — Consumer Price Index, rent of primary residence and all items, New York-Newark-Jersey City (CUURS12ASEHA, CUURS12ASA0) (monthly to August 2026, retrieved 25 September 2026; no October 2025 index was published) — January to August averages: rent up 9.4% from 2024 to 2026 and 26.3% from 2019; all items up 7.9% from 2024
- U.S. Bureau of Labor Statistics — Current Employment Statistics, average hourly and weekly earnings of all employees, total private, New York City (SMU36935610500000003, SMU36935610500000011) (monthly to August 2026 (latest month preliminary), retrieved 25 September 2026) — January to August averages: hourly earnings up 6.9% from 2024 to 2026 and 20.6% from 2019; weekly earnings up 6.7% from 2024
- NYC Rent Guidelines Board — 2025-26 Apartment and Loft Order #57 (adopted 30 June 2025) — 3% for one-year and 4.5% for two-year renewal leases of rent-stabilised apartments beginning 1 October 2025 to 30 September 2026
- NYC Rent Guidelines Board — Adopted Summary of Guidelines (2026-27) (adopted 25 June 2026) — 0% for one-year and two-year renewal leases beginning 1 October 2026 to 30 September 2027
- U.S. Census Bureau — American Community Survey news: 2026 updates (update of 6 August 2026) — the release date for the 2025 ACS one-year estimates is being determined while the Bureau works to a new Commerce Department order on disclosure avoidance; why the census figures here stop in 2024
How to cite
Reference
BibTeX
Quote the version: a correction bumps it, and the corrections log says what changed. Charts can be embedded from the “Embed this chart” link under each one.